| 2006 – 2026 | Strategy | Same 1/3 weights, buy & hold | SPY buy & hold |
|---|---|---|---|
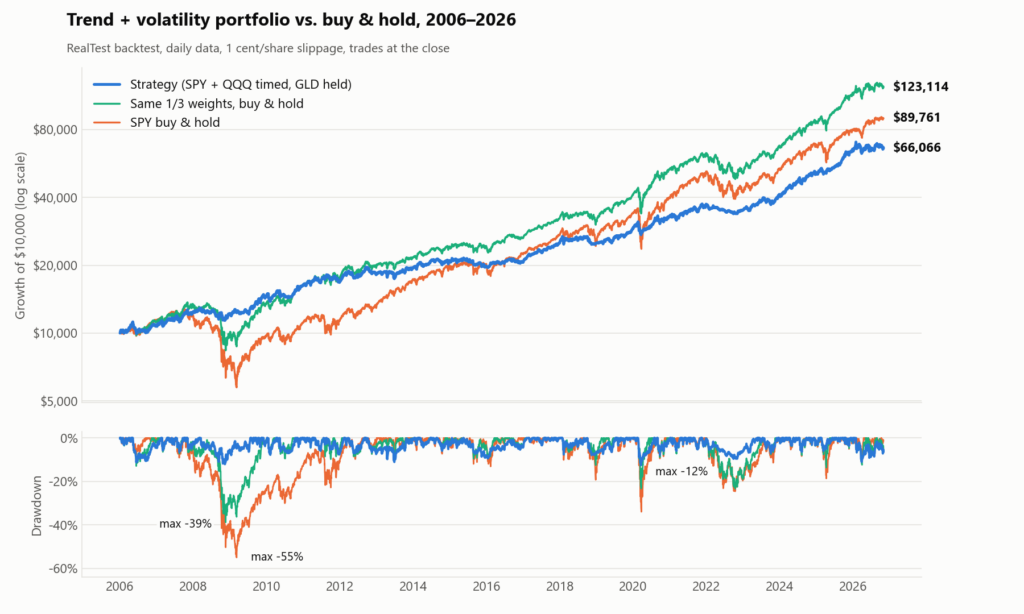
| Annual return (CAGR) | 9.5% | 12.8% | 11.1% |
| Maximum drawdown | −12.5% | −38.8% | −55.0% |
| Return / max drawdown (MAR) | 0.76 | 0.33 | 0.20 |
| Sharpe ratio | 0.98 | 0.88 | 0.65 |
| 2008 | −1% | −26% | −36% |
| 2022 | −6% | −17% | −18% |
| Worst calendar year | −6% | −26% | −36% |
| $10,000 became | $66,066 | $123,114 | $89,761 |
Why I started digging
I know the textbook answer as well as anyone: buy an index fund and never sell. Over the last 20 years, SPY turned $10,000 into almost $90,000.
But I’ve seen what happens in between. To actually earn that return, you had to sit through a 55% loss in 2008 without selling. Then 34% in five weeks in 2020. Then another 25% in 2022. Very few people manage that. They sell somewhere near the bottom, buy back after the recovery, and their real return ends up far below the index.
So the question that kept me busy was a different one: how much of the market’s return can I keep if I simply refuse to lose more than a modest amount?
My starting point was a simple SPY trend filter based on EMAs that I had been using for a while. This time I gave it the stress test it deserved: around 400 backtests, walk-forward validation, tests on ETFs it had never seen, and a portfolio built only from the pieces that survived. Most ideas failed – some of them very popular ones. Two almost boring building blocks survived everything I threw at them.
The result is the portfolio in the chart above. Its worst drawdown in 20 years was 12.5%. It lost 1% in 2008. Its worst calendar year was −6%. And it still compounded at 9.5% a year.
Why this matters to me
Losses hurt more than gains help. A 55% loss needs a 122% gain just to get back to even. A 12.5% loss needs 14%. After 2008, SPY needed until 2012 to recover. This portfolio was back at new highs by mid-2009.
It still takes part when markets rise. This isn’t a system that hides in cash for years. On average about 78% of the money is invested, and in calm, rising markets the stock part is fully in. Positions shrink when things get turbulent and only go to cash when the long-term trend actually breaks.
Three engines instead of one. The portfolio combines the broad US market, large-cap tech and gold – and gold has often held up or even risen exactly when stocks were in trouble. Each stock sleeve follows its own trend signal, so one false signal never moves the whole portfolio.
Something I can actually stick with. The best strategy is the one you are still following in year three. With a worst year of −6%, there is very little temptation to throw the plan away at exactly the wrong moment.
Simple, and tested honestly. Four rules, daily data, three liquid ETFs, at most one decision a day. I checked the parameters with walk-forward analysis, which only uses data that was available at the time, tested the rules on ETFs they were never fitted to – and I’m showing you the variants that failed, too.
The honest trade-off: over this period, simply holding the same three ETFs without any timing earned more – 12.8% against 9.5% a year. This strategy is for people who value a smooth ride and staying invested over squeezing out the last percent. If you can genuinely sit through a 40–55% loss without flinching, buy & hold may serve you better.
PREMIUM SECTION – the full research, the exact rules and the source code.
This part is for paying readers
Buy lifetime access to the full post. After payment you will receive a sign-in link by email.
Already bought this post? Sign in
Each RealTest file includes its own data import section. Expect small differences on QuantConnect, which uses different price data, dividend adjustment and its default fee model.
This article is for educational purposes only and is not investment advice. Backtested results are hypothetical, do not reflect actual trading, and do not guarantee future performance.